
Your Objectives First
We agree what you are trying to achieve, your budget and your timeframe before we look at any development. Your brief becomes the test every opportunity has to pass.

Independent-minded property advisory for South African investors seeking carefully selected UK off-plan opportunities. We take the time to understand your investment objectives, available capital and long-term plans before identifying property opportunities worth considering.
Investor-led advice. Carefully selected developments. A more considered approach.
A private, no-obligation conversation with the founder.
Many UK off-plan opportunities reach South African investors through sales channels built to move a developer's available stock. The conversation starts with what needs to be sold.
Alderstone works the other way round. Before we discuss any development, we take time to understand your circumstances: what you want the investment to do for you, the capital you are comfortable committing, how long you intend to hold, and the risks you are and are not prepared to take.
Opportunities are then sourced through our relationships with selected UK developers and assessed against your brief before they are presented. If nothing suitable is available, we will tell you.
Four principles shape every conversation we have with an investor, from the first consultation to completion and beyond.
We agree what you are trying to achieve, your budget and your timeframe before we look at any development. Your brief becomes the test every opportunity has to pass.
We work with a selected network of UK developers and review each scheme before presenting it. You see a short list of relevant options, not a catalogue.
We set out the risks and costs alongside the potential. You should understand what could go wrong, as well as what could go right, before committing capital.
You deal with the same advisor throughout, by video call, phone or in person when we are in South Africa. Long-term relationships matter more to us than single transactions.
For many South African investors, UK rental property offers an opportunity to diversify a portfolio that may otherwise be concentrated in a single country and currency, while benefiting from an established legal framework, strong tenant demand and a globally recognised property market.
The UK has a substantial private rented sector, supported by long-term structural factors: affordability, population growth, changing lifestyles and employment centres.
New housing delivery has struggled to keep pace with the country's housing requirements, particularly in areas experiencing strong population and employment growth, underpinning rental demand.
One of the strongest attractions for South African investors is the opportunity to generate income in British pounds.
The UK offers investors confidence through a well-established legal system, transparent property ownership and strong protection of property rights. Supported by HM Land Registry, regulated conveyancing processes and an independent judiciary, the market provides a clear and structured framework for property transactions, ownership and contractual enforcement.
The UK property market has a long-term track record of capital growth, underpinned by a persistent shortage of housing and sustained demand for residential property.
Unlike some property markets, the UK allows overseas investors to purchase residential property without needing UK residency or citizenship. South African buyers can also appoint UK-based solicitors, letting agents and property managers to oversee the investment remotely.
For investors whose wealth is concentrated in one country, currency or asset class, UK property offers another way to spread investment risk.
Markets move in both directions. Exchange-rate movements can reduce the value of your investment and income when measured in rand. UK property values and rents can fall as well as rise, and changes in interest rates, regulation or tax can affect returns.
Buying off-plan means committing to a property before it is built or finished. It has its own sequence, costs and risks, which we take you through in three stages.
Capital appreciation, completion dates, rental income and investment returns are not guaranteed. Developments can be delayed, valuations at completion can differ from the purchase price, and mortgage terms can change during the build period.
Every opportunity we present has been through the same five steps. The order matters: we understand you first, and assess the property second.
A structured consultation covering goals, capital, timeframe, financing and appetite for risk.
We review current and upcoming schemes from our developer network against your brief.
Location, pricing against comparable stock, developer credentials, rental demand and total cost of ownership.
A short list with the reasoning, the costs and the risks for each, so you can compare like with like.
If you decide to proceed, we coordinate the purchase with your solicitor, lender and advisors.
You receive considered options, not an indiscriminate list of developments.
Investing from South Africa adds exchange-control, tax and structuring questions that need proper professional advice. We help you understand the questions to ask and coordinate with qualified specialists who can answer them.
Transfers from South Africa are subject to South African Reserve Bank exchange-control rules and SARS requirements, which can include tax compliance approval for larger amounts. Applicable allowances and processes change, so they should be confirmed with your authorised dealer or tax practitioner before you commit to a payment schedule.
Property can be held in your own name, jointly, or through a UK company. Each route has different implications for tax, financing, administration and estate planning. A company structure is not automatically more efficient, and it does not on its own remove UK inheritance tax exposure.
UK rental income, capital gains and inheritance tax may apply to UK property, and South African tax residents are generally taxed on worldwide income. The UK and South Africa have a double taxation agreement, which can affect how tax paid in one country is treated in the other. How it applies depends on your circumstances.
Some UK lenders offer mortgages to non-UK residents, often with larger deposit requirements and stricter criteria than for UK residents. Mortgage interest relief rules differ between individuals and companies and should not be assumed. Your ability to borrow at completion is assessed at that point, not when you reserve.
We work alongside qualified UK solicitors, mortgage brokers, cross-border tax advisors and exchange-control specialists, and can introduce you where helpful. Your own existing advisors are always welcome to be involved.
Alderstone does not provide tax, legal, exchange-control or regulated financial advice. The information above is general and should not be relied upon in place of advice from a suitably qualified professional who understands your circumstances.
A selection of developments we have introduced to investors from our UK developer network. Availability changes quickly, so we share current units, floor plans and pricing privately once we understand your brief.

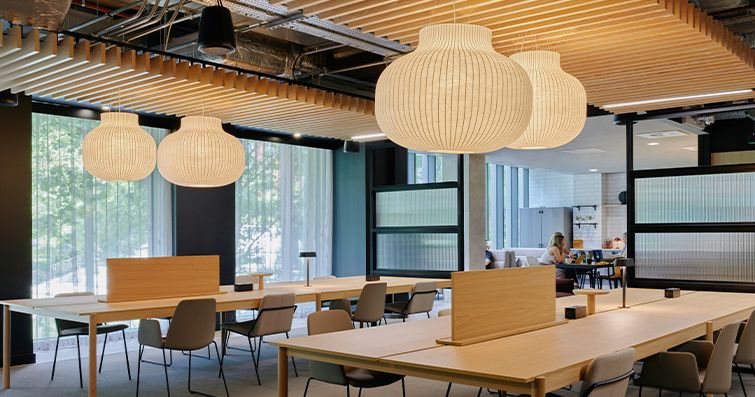
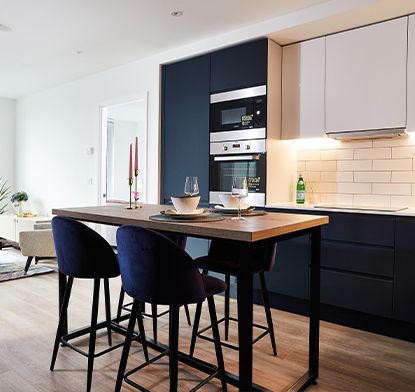
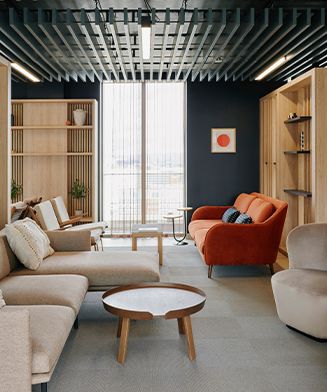
Luxury Residential Living
Occupying a prominent position in Manchester city centre, Vita Living Circle Square North offers 35 storeys of luxury, designed to appeal to the city's abundance of young professionals. Boasting an M1 postcode, Sky Lounge with 300-degree city views, fully-equipped gymnasium, market-leading co-working space, and 15th-floor resident lounge with two terraces and private dining rooms, this residence is perfecting high-life living.

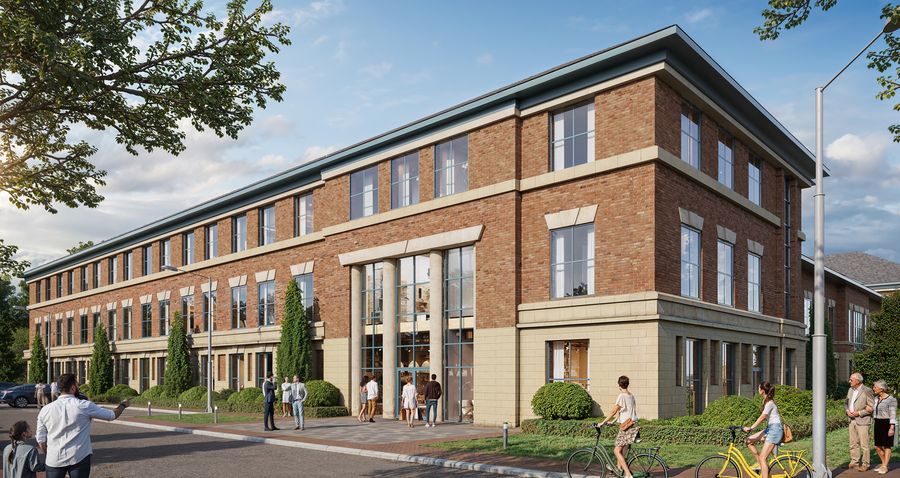
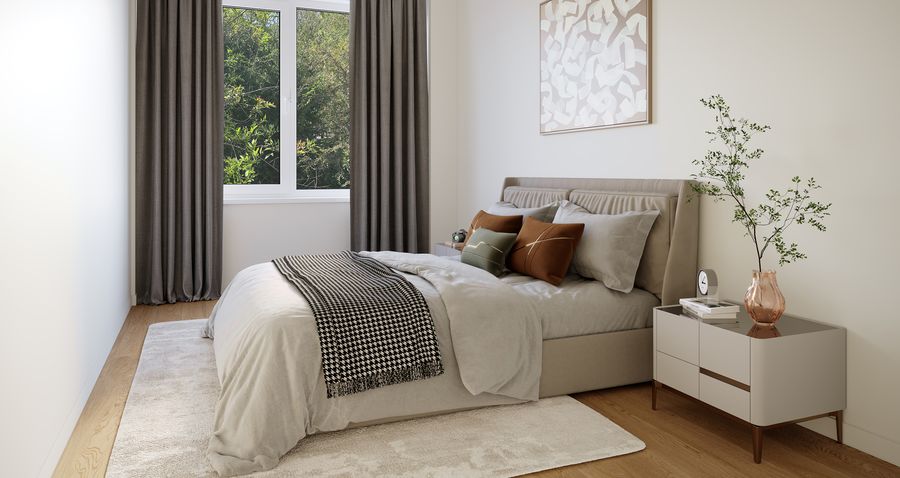
Luxury residential apartments
Lakeside comprises 118 contemporary one- and two-bedroom apartments within private grounds on the banks of the River Leen, with the most extensive in-house amenities of any development in Nottingham. Wellness-focused features are designed for strong tenant appeal.

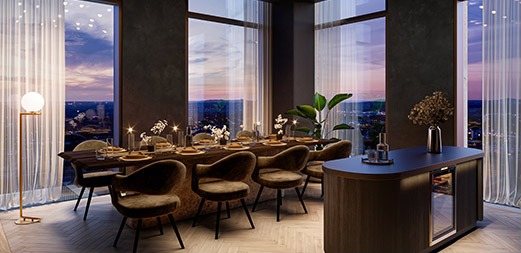
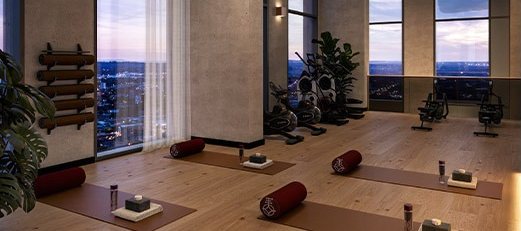
Premium luxury residential new build
Home to 432 luxury one- and two-bedroom apartments, the development has been designed to offer residents far more than a place to live. Wellness, leisure, fitness and social spaces are thoughtfully integrated throughout, creating an elevated living experience.
Residents can enjoy an extensive wellness offering, including a 20-metre swimming pool, hydro-pool, steam room, sauna and ice plunge pool. Fitness facilities are equally impressive, with a 44th-floor gym featuring an external terrace, a dedicated spin studio and a state-of-the-art yoga studio.
For those seeking something different, a spectacular two-storey climbing wall spans the 44th and 45th floors, while the 45th-floor Sky Lounge provides an exceptional setting to work, relax and socialise. Featuring co-working facilities, private dining and Sky Play, complete with a golf simulator and shuffleboard, these spaces bring a new dimension to modern city living.
Prices, payment plans, projected yields and completion dates are supplied by the developer, are indicative only and may change. Gross yields are before costs such as service charges, management fees, insurance, voids, mortgage costs and tax, so net returns will be lower. Images are photographs or computer-generated images for illustration only.
Alderstone acts as your coordinating point throughout. Developers, solicitors, lenders and tax specialists each play their part, and we keep the process connected so you are not managing it alone from another country.
A private conversation about your objectives, capital, timeframe and questions. There is no obligation to proceed.
We present a short list of assessed options with costs, risks and our reasoning, and answer your questions on each.
You reserve your chosen property. Your UK solicitor reviews the contract and carries out searches before exchange.
The property is finished and inspected, and the balance is paid from your funds or a mortgage arranged ahead of time.
Letting and management are put in place, and tax reporting is handled with your specialists in both countries.
Alderstone Property Advisory is a specialist advisory business helping South African investors approach UK off-plan property with clarity and care.
We built Alderstone around a simple belief: the right property depends on the person buying it. Our work is relationship-led. We would rather help an investor make one well-considered decision than many hurried ones.

Grant brings over 20 years of corporate asset finance experience and more than 15 years of property investment experience to Alderstone Property Advisory.
An active international property investor since 2008, Grant has built a multi-million-pound property portfolio spanning South Africa, the United States and the United Kingdom. His experience across these markets gives him a practical understanding of the opportunities, considerations and challenges involved in building and managing an international property portfolio.
Since 2020, Grant has advised UK and international clients on UK property investment, helping investors identify opportunities aligned with their individual objectives, financial circumstances and longer-term plans.
Having lived in the UK for 22 years, he has developed extensive knowledge of its regional property markets, with experience across many of the country's major regional cities. He has also established strong relationships with UK developers, founded on a collaborative approach that places the investor's interests and objectives at the centre of the process.
At Alderstone, Grant believes that property advice should begin with the client, not with the available stock. By understanding what an investor wants to achieve before exploring potential opportunities, he aims to bring greater clarity, relevance and a more considered approach to every investment decision.
General answers to the questions South African investors ask most often. Your own situation may differ, and we will always point you to the right specialist for advice.
Off-plan property
You agree to buy a property before construction is finished. You usually pay a reservation fee, then one or more deposits during the build, with the balance due at completion. The exact payment structure varies between developments and is set out in the contract your solicitor reviews.
Delays are a real possibility with any construction project. Contracts normally include a long-stop date and set out what happens if it is missed. How your deposits are held and protected also differs by development. Your solicitor should explain these terms before you exchange.
Buying from South Africa
Yes. Non-UK residents can buy UK residential property. You will need a UK solicitor, identity and source-of-funds checks, and a compliant way of moving funds from South Africa. Additional Stamp Duty Land Tax charges may apply to non-UK residents.
Not necessarily. Consultations, legal work and completion can usually be handled remotely. Many investors still choose to visit a location or development before committing, and we can help arrange this.
Funding
Some UK lenders lend to non-residents, but the choice is narrower and criteria are usually stricter, often with larger deposits required. With off-plan purchases, the mortgage is assessed near completion, so rates and availability may differ from when you reserved. A specialist mortgage broker can advise on your options.
Funds are typically transferred through an authorised dealer or foreign exchange provider within South African Reserve Bank and SARS requirements. Allowances and approval processes change from time to time, so confirm the current position with your provider or tax practitioner and plan transfers around your payment milestones.
Taxes
UK property can give rise to UK tax on rental income and gains, and South African tax residents are generally taxed on worldwide income. The UK–South Africa double taxation agreement can affect how tax paid in one country is credited in the other. Please take advice from a cross-border tax specialist before you buy.
It depends on your circumstances. A company can change how income, interest costs and gains are taxed and how the property is financed, but it brings its own costs and filing duties. It does not automatically remove inheritance tax exposure, and it does not guarantee full relief on mortgage interest. Professional advice is essential.
Risks
The main risks include construction delays or developer difficulties, a valuation at completion below the purchase price, changes in mortgage availability or interest rates, periods without a tenant, rising ongoing costs, changes in tax or regulation, and exchange-rate movements. Property can also take time to sell.
Alderstone may receive commission or referral fees from developers when a client buys a property we have introduced. We disclose these arrangements before you commit, so you can weigh them in your decision.
Whether you are considering your first UK property investment or looking to expand an existing portfolio, the starting point is understanding what you want to achieve.
Share a few details and we will contact you to arrange a convenient time.